Thinking of buying a flat or villa in Dubai while you live in India? It is very doable. But the money side works differently from buying in Mumbai, Bangalore or Delhi. Indian rules decide how much you can send abroad, how it is taxed at the time of sending, and what you must report afterwards. Dubai rules decide where you can buy, how your payments are protected and what fees you pay.
This guide walks through both sides, step by step, for resident Indians (people who live in India and send money under the RBI's Liberalised Remittance Scheme) and briefly for NRIs already living abroad. It uses official sources first: the Reserve Bank of India (RBI), the Income Tax Department, the Dubai Land Department (DLD), Dubai's legislation portal and the UAE government portal. It is general information only, so speak to a chartered accountant in India and a UAE lawyer before you commit.
Exchange rate used in this guide (26 October 2026): AED 1 = INR 25.92 (Wise mid-market rate, 26 October 2026). Cross-check: the ECB reference rate on 23 October 2026 was USD 1 = INR 94.94, which with the UAE dirham's fixed peg of AED 3.6725 per US dollar works out to about AED 1 = INR 25.85. INR figures are rounded and for illustration only; your bank's rate on the day you remit will differ.
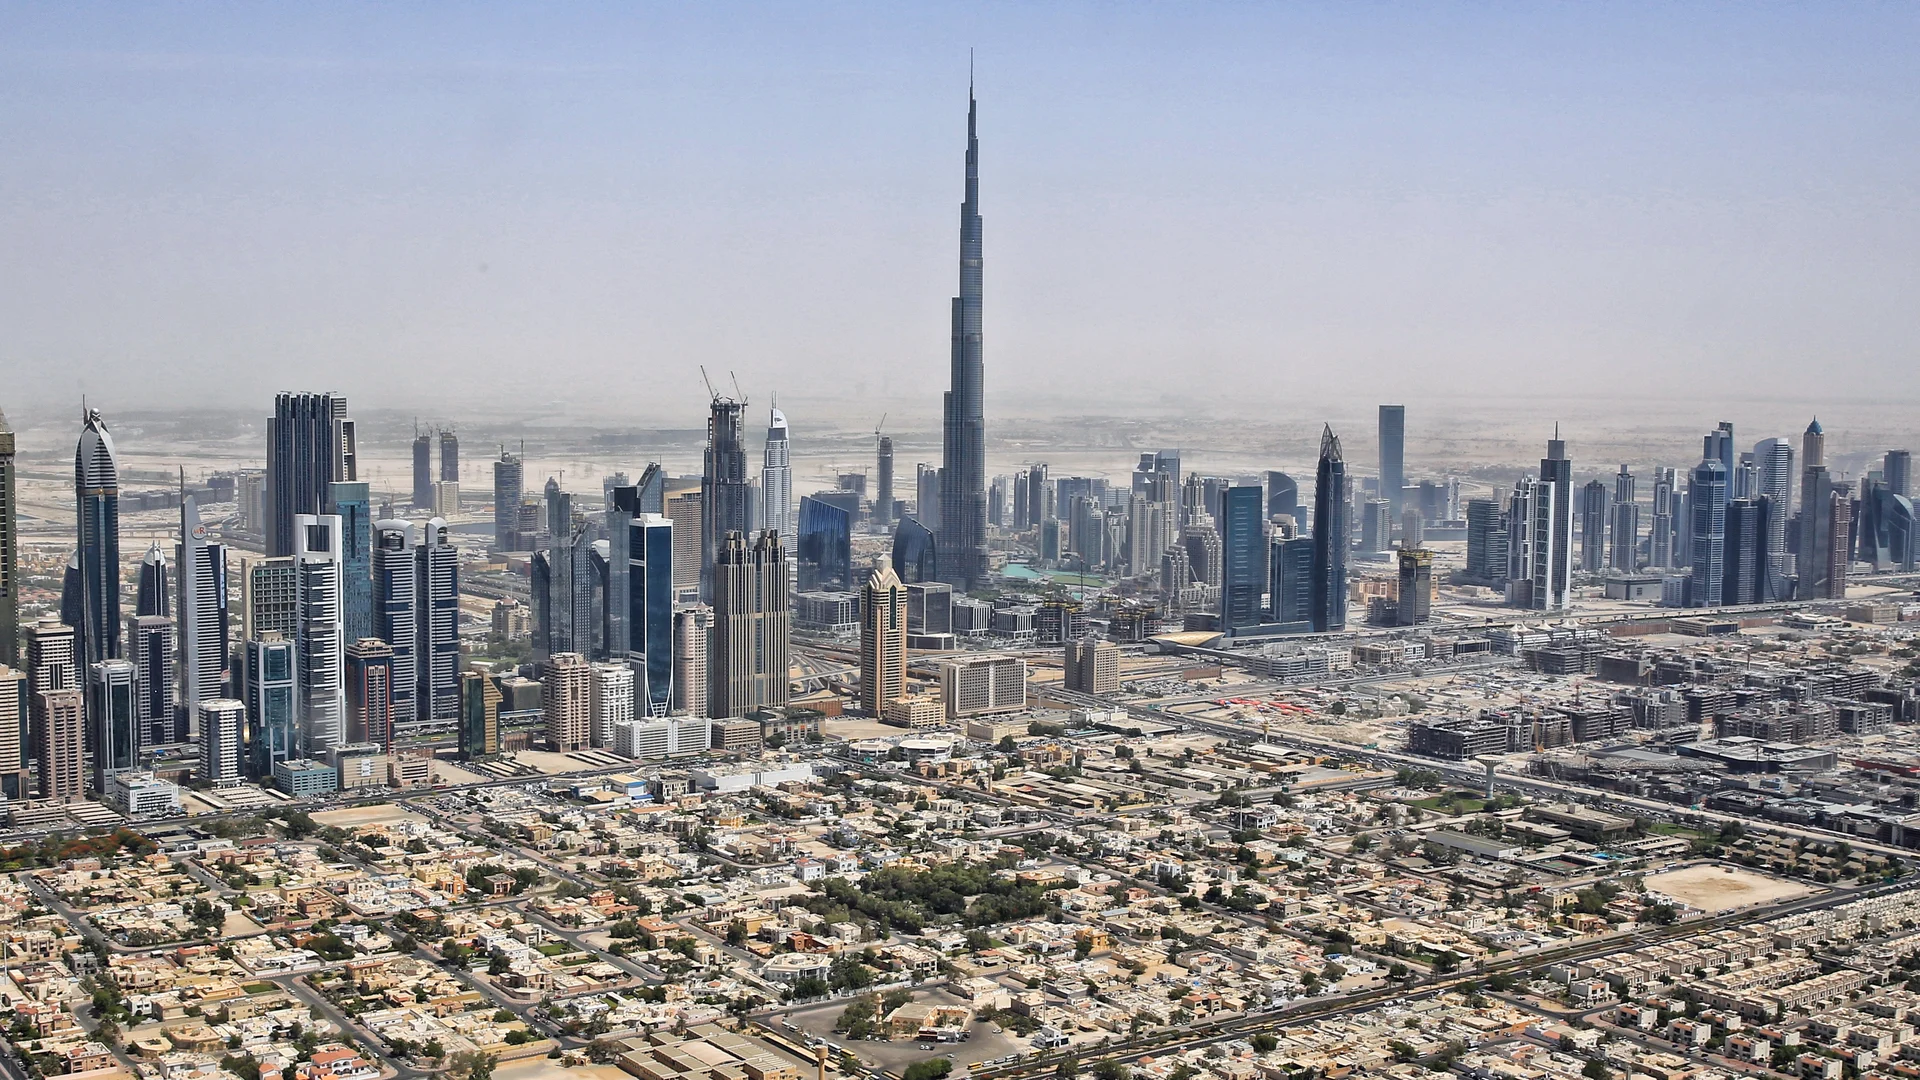
Credit: Tim Reckmann, via Wikimedia Commons, CC BY-SA 3.0
The short answer
| Can an Indian buy property in Dubai? | Yes. Foreign nationals, including Indians, can buy freehold property in the areas of Dubai designated for foreign ownership |
|---|---|
| Can a resident Indian send money for it? | Yes. The RBI allows resident individuals to remit money under the Liberalised Remittance Scheme (LRS) to buy immovable property outside India |
| How much can I send? | Up to USD 250,000 per person per financial year (April to March), about AED 918,000 or INR 2.38 crore, across all LRS purposes combined |
| Tax collected when I send it | Your bank collects TCS (tax collected at source) of 20% on LRS remittances above INR 10 lakh in a financial year for purposes such as property. You can claim it as a credit in your income tax return |
| Main Dubai fee | DLD registration fee of 4% of the price, listed as 2% buyer and 2% seller; the sale contract decides who actually pays |
| After you buy | Resident Indians must report the property in the foreign assets schedule (Schedule FA) of their income tax return, and rent or gains may be taxable in India |
Step 1: Check which rules apply to you
Your residential status decides almost everything on the Indian side.
- Resident Indian (living in India): you send money under the LRS, your bank collects TCS above the threshold, and you report the property in your Indian tax return. Most of this guide is about you.
- NRI (living and earning abroad, for example in the UAE): the LRS is a scheme for residents of India, so it does not limit money you have earned abroad. Many NRIs in the UAE simply pay from their UAE salary or savings. If you later return to India, the RBI confirms that a resident can continue to hold foreign property they acquired while they were a non-resident.
Income tax residency (based mainly on days spent in India) and FEMA residency are tested differently, so if you split your time between countries, ask a chartered accountant which side of the line you fall on before you remit.
Step 2: Understand the LRS limit and plan your payments
Under the Liberalised Remittance Scheme, every resident individual, including minors, can remit up to USD 250,000 per financial year for permitted current or capital account transactions, and buying immovable property outside India is one of them. You need a PAN to remit, and anything above USD 250,000 needs prior RBI permission.
Three things matter in practice:
- The limit covers all your LRS spending. Foreign holidays, education fees and overseas investments sent through LRS in the same year all come out of the same USD 250,000.
- Family members can combine their limits for property. The RBI allows remittances for buying property abroad to be consolidated among relatives who are resident in India, as long as each of them complies with the scheme. In practice, that usually means each remitting family member should be a co-owner of the property. Check the paperwork with your bank first.
- Each financial year has a fresh limit. An off-plan payment plan that spreads instalments over several April to March years can keep each year's payments inside the limit, which is one reason off-plan is popular with Indian buyers. Our explainer on a Sobha 20/80 payment plan shows how a typical plan is structured.
| Example | AED | INR (approx.) | Within one person's LRS limit in one year? |
|---|---|---|---|
| One person's annual LRS limit (USD 250,000) | 918,125 | 2.38 crore | The limit itself |
| Ready studio or one-bedroom flat at AED 900,000 | 900,000 | 2.33 crore | Only just, and only if you have used almost no other LRS that year |
| Ready apartment at AED 1,500,000 paid in one go | 1,500,000 | 3.89 crore | No. You would need co-owner relatives remitting too, or RBI permission |
| Off-plan apartment at AED 1,500,000, 20% now and the rest over later years | 300,000 now | 77.8 lakh now | The first instalment, yes; later years depend on that year's schedule |
Unused money must come back. RBI rules say foreign exchange sent under LRS that is not used or reinvested must be brought back and surrendered to an authorised dealer within 180 days. So don't park large sums in a Dubai account long before they are due; time each remittance to the payment date in your contract.
Step 3: Budget for TCS when you remit
TCS is not an extra tax on top of your income tax. It is an advance collection that your bank deducts at the time of remittance and deposits against your PAN. The Income Tax Department's TCS rates say no TCS is collected on the first INR 10 lakh of LRS remittances in a financial year (about AED 38,600), and for purposes other than education and medical treatment, which includes buying property, TCS is 20% of the amount above INR 10 lakh. Banks confirm the same rates continue for the 2026-27 financial year. The threshold is combined across all your LRS payments and all banks.
Worked example: you send AED 900,000 (about INR 2.33 crore) in one financial year and have made no other LRS payments. TCS is 20% of roughly INR 2.23 crore, so the bank collects about INR 44.7 lakh up front. You get a TCS certificate, and you can claim the amount as a credit when you file your return, against your tax for that year or as a refund. That is a large amount of cash tied up until you file, so plan for it, and ask your CA whether spreading payments across years or among co-owners changes your cash flow.
Step 4: Choose the area and the property
Indian buyers are foreign nationals under Dubai law, so you can own freehold property in the areas designated for foreign ownership. That includes most of the places people mean when they talk about investing in Dubai, such as Downtown Dubai, Business Bay, Dubai Marina, Dubai Creek Harbour and the master-planned villa communities.
Then decide between off-plan and ready:
| Off-plan (from the developer) | Ready or resale | |
|---|---|---|
| How you pay | In stages under a payment plan, into the project's escrow account | Usually in full at transfer, unless you take a mortgage |
| Fit with the LRS limit | Easier, because instalments can fall in different financial years | Harder for larger purchases, because most of the price is due at once |
| Registration | Contract registered on DLD's interim register (Oqood) | Title deed issued at a DLD trustee office on transfer day |
| Rent | None until handover | You can let it straight away |
| Main risk | Construction delays; buying from plans and renders | Condition of the unit and any existing tenancy |
For current options, see our round-up of Dubai off-plan launches in October 2026 and our Dubai townhouses report for 2026. If you are worried about timing, our look at what history actually shows about Dubai market crashes is worth a read.
Credit: Lxs, via Wikimedia Commons, CC BY 4.0
Step 5: Check the developer, the escrow account and the agent
- Escrow: under Dubai Law No. 8 of 2007, a developer selling off-plan must open a separate escrow account for each project, and buyers' payments go into it. Send your money only to the escrow account named in your contract, never to a personal account.
- Interim registration: off-plan sales must be registered on DLD's interim real estate register. Ask when your registration certificate will be issued.
- Broker: use a DLD-registered brokerage and ask to see the agent's DLD broker card.
- Contract: check the handover date, late-delivery terms, the payment schedule, service charges and resale terms. A UAE lawyer can review it for you.
Step 6: Send the money through your bank
Remittances under the LRS go through an authorised dealer bank in India. Expect to:
- give your PAN (it is mandatory for LRS) and fill in the bank's LRS declaration, usually Form A2, stating that the purpose is buying immovable property abroad
- show the sale agreement or developer's payment demand, with the escrow account details
- show where the money came from, such as bank statements or sale proceeds
- pay TCS on the part above the INR 10 lakh threshold
On the Dubai side, the developer, agent, trustee office or bank will also ask for proof of source of funds under UAE anti-money laundering rules, so keep the remittance records together.
Step 7: Sign, register and get your title deed
You can view and sign in person, which is a short flight from most Indian metros, or appoint a representative under a power of attorney. Ask a UAE lawyer to draft it and confirm how it must be notarised and attested in India so Dubai authorities accept it.
For a ready property, the transfer happens at a DLD Real Estate Registration Trustee office. DLD lists the documents as identification of both parties (Emirates ID, or a valid passport for non-resident foreigners) and a no-objection certificate from the developer in freehold areas. DLD then issues an electronic title deed. For off-plan, you receive the interim registration first and the title deed after handover.
What it costs: DLD fees in AED and INR
DLD's published fees for registering the sale of a ready property:
| Fee | AED | INR (approx.) |
|---|---|---|
| DLD registration fee | 4% of the price (listed as 2% buyer, 2% seller) | 4% |
| Trustee office (service partner) fee, sale value AED 500,000 (INR 1.30 crore) or more | 4,000 + VAT | 1.04 lakh + VAT |
| Trustee office fee, sale value below AED 500,000 | 2,000 + VAT | 51,840 + VAT |
| Title deed issuance | 250 | 6,480 |
| Villa or apartment map | 250 | 6,480 |
| Knowledge fee and innovation fee | 10 each | 259 each |
Worked example: a ready apartment at AED 1,500,000
This assumes your contract makes you, the buyer, pay the full 4% DLD fee. If it is split with the seller, your share is lower.
| Item | AED | INR (approx.) |
|---|---|---|
| Purchase price | 1,500,000 | 3.89 crore |
| DLD fee at 4% | 60,000 | 15.55 lakh |
| Trustee fee incl. 5% VAT | 4,200 | 1.09 lakh |
| Title deed, map, knowledge and innovation fees | 520 | 13,480 |
| Government and trustee costs | 64,720 | 16.78 lakh |
Not included: agency commission, developer NOC fees on resales, bank charges on each remittance, the TCS your bank collects in India, and annual service charges. Ask for all of them in writing. Our guide to Dubai property taxes and fees covers the wider costs.
After you buy: tax and reporting in India
- UAE side: the UAE government says it does not levy income tax on individuals. Under the UAE Corporate Tax rules, income an individual earns from investing in real estate in their personal capacity, without needing a licence for it, is outside corporate tax. Licensed holiday-home letting can be treated differently, so check before you list on short-let platforms.
- India side: residents of India are generally taxed on their worldwide income, so rent from a Dubai flat and any gain when you sell may be taxable in India. India and the UAE have a double taxation avoidance agreement, but because the UAE usually charges no personal tax on rent, there is often no UAE tax to offset.
- Reporting: the Income Tax Department requires resident taxpayers to disclose foreign assets, including immovable property outside India, in Schedule FA of the income tax return, even if their income is below the taxable limit. The simpler ITR-1 and ITR-4 forms don't have this schedule, so you will need a fuller return form. Missing this disclosure can lead to serious penalties under India's black money law.
- Rental income abroad: RBI rules allow you to retain and reinvest income earned on LRS investments, but foreign exchange that is not reinvested must be brought back within 180 days. Ask your bank how that applies to your rent.
India's new Income-tax Act, 2025 applies from 1 April 2026, so section numbers and form names may differ from older articles you find online. Treat this section as general information and confirm your position with a chartered accountant.
The Golden Visa angle
Many Indian buyers ask about residency. The UAE government portal lists real estate investors among the Golden visa categories, with a minimum capital of AED 2 million (about INR 5.18 crore). Owning property does not automatically give you a visa, and the conditions, duration and documents are set by the UAE's federal identity authority (ICP) and Dubai's residency department (GDRFA), so check their current requirements before you buy with a visa in mind. Our article on Dubai's investor visa update for 2026 covers the latest changes.
Practical tips for Indian buyers
- Plan the money before you pick the unit. Work out each family member's LRS headroom and the TCS cash flow first.
- Buy in the names of the people remitting. It keeps the LRS paperwork clean.
- Pay only into escrow or official accounts, and keep every remittance advice and TCS certificate.
- Check the developer's track record with DLD records and recent sale prices, not just the brochure.
- Tell your CA in the same year you buy, so Schedule FA and any rent are reported correctly from the start.
How Luxwell helps Indian buyers
Luxwell Real Estate is a boutique luxury real estate brokerage based in Churchill Executive Tower, Business Bay. We handle off-plan and ready sales and help clients buy, sell and lease across Dubai, and Luxwell ranks in Bayut's top 5 agencies most months.
Our team, led by Chief Sales Officer Nikhil Wadhwa and Chief Operating Officer Divya Wadhwa, can shortlist projects with payment plans that suit the LRS limit, compare recent DLD prices, check escrow details and arrange video or in-person viewings around your trip. We don't give legal, tax or foreign exchange advice, but we work alongside your CA and lawyer.
- Call: +971 50 856 2749
- WhatsApp: +971 50 856 2749
- Email: info@luxwellrealestate.com
- Website: www.luxwellrealestate.com
This article is general information only and is not legal, tax, foreign exchange or financial advice. Rules change and depend on your circumstances. Speak to a chartered accountant in India and a UAE lawyer before making decisions. Information checked 26 October 2026.
Sources
- Reserve Bank of India: FAQs on the Liberalised Remittance Scheme, FAQs on acquiring immovable property outside India and Master Direction on the Liberalised Remittance Scheme
- Income Tax Department: TCS rates, Schedule FA, details of foreign assets and brochure on declaring foreign assets and income
- Dubai Land Department: Property sale registration and Know Your Rights investor guide
- Dubai Legislation Portal: Law No. 8 of 2007 Concerning Escrow Accounts
- UAE Government portal: Taxation and Golden visa; Federal Tax Authority: Taxation of natural persons under the Corporate Tax Law
- Exchange rates: Wise mid-market AED to INR, 26 October 2026; ECB reference rate via Frankfurter, 23 October 2026; UAE dirham peg AED 3.6725 per USD
Frequently Asked Questions
Can an Indian citizen buy property in Dubai?
- Yes. Indian citizens, like other foreign nationals, can buy freehold property in the areas of Dubai designated for foreign ownership, which include Downtown Dubai, Business Bay, Dubai Marina and Dubai Creek Harbour.
How much money can I send from India to buy property in Dubai?
- Under the RBI's Liberalised Remittance Scheme, a resident individual can remit up to USD 250,000 per financial year (April to March), about AED 918,000 or INR 2.38 crore at 26 October 2026 rates, for all permitted purposes combined, including buying property abroad. Amounts above that need prior RBI permission.
Can family members combine their LRS limits to buy one property?
- The RBI allows remittances for buying immovable property outside India to be consolidated among relatives who are resident in India, as long as each of them complies with the scheme's terms. In practice each remitting relative is usually a co-owner, so check the paperwork with your bank first.
How much TCS is charged when sending money abroad for property?
- According to the Income Tax Department, no TCS is collected on the first INR 10 lakh of LRS remittances in a financial year, and for purposes other than education and medical treatment, including property, TCS is 20% of the amount above INR 10 lakh. TCS can be claimed as a credit in your income tax return.
Do NRIs need to use the LRS to buy property in Dubai?
- No. The LRS is a scheme for residents of India. An NRI living and earning abroad, for example in the UAE, can usually pay from their foreign income or savings. The RBI also confirms that a person who returns to India can keep foreign property acquired while they were non-resident.
What fees do I pay when buying property in Dubai?
- The main fee is the Dubai Land Department registration fee of 4% of the price, listed as 2% buyer and 2% seller, with the contract deciding who pays. For ready sales of AED 500,000 or more there is a trustee office fee of AED 4,000 (about INR 1.04 lakh) plus VAT, and small title deed and map fees. Rate used: AED 1 = INR 25.92 on 26 October 2026.
Do I have to declare Dubai property in my Indian income tax return?
- Yes, if you are resident in India. The Income Tax Department requires resident taxpayers to disclose immovable property outside India in Schedule FA of the return, even if their income is below the taxable limit. ITR-1 and ITR-4 don't include this schedule, so a fuller return form is needed. Ask a chartered accountant.
Is rental income from Dubai property taxed?
- The UAE does not levy income tax on individuals. If you are resident in India, rent and gains from Dubai property may be taxable in India because residents are generally taxed on worldwide income. Confirm your position with a chartered accountant.
Related reading
- Dubai Off-Plan Launches October 2026: Every New Launch in Dubai This Month
- Understanding Dubai Property Taxes: The Ultimate 2025 Guide for Investors
- Dubai Removes AED 750,000 Minimum Requirement for Investor Visa (Update 2026): What It Means for Real Estate Buyers
- Sobha 20/80 Payment Plan, 7–16 October 2026: Sobha Central, Hartland II, Solis and Orbis
- Nikhil Wadhwa – Chief Sales Officer, Luxwell Real Estate
Request details
Leave your details to download the details